

Payday Cash Advance TriceLoans
by Trice Loans
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 50.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
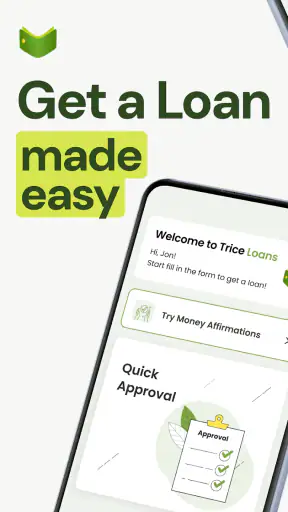
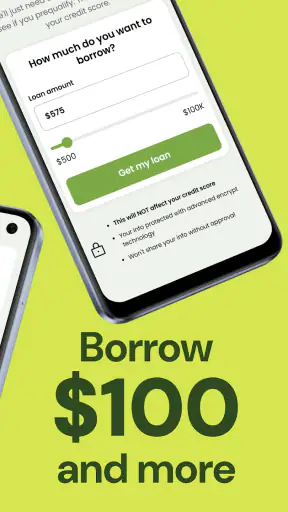
 Analysis by Getfullapps
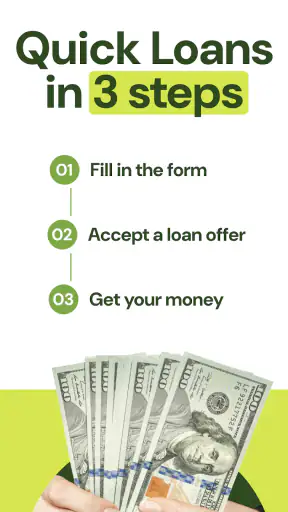
I approached Payday Cash Advance TriceLoans as a practical finance app rather than as a general budgeting tool. Its purpose is narrow: it is built around helping users seek a payday cash advance through a mobile loan application, with an emphasis on a quick application experience and no credit check. That focus can be useful when a short-term cash gap feels urgent, but it also means the app deserves a more careful look than a typical free utility.
Trice Loans is the developer behind the app, which is listed in the Finance category and available free of charge. The app is rated for Everyone, runs on Android 7.0 or later, and its current version is 1.1.6. It has reached over 50 thousand installs, with a 4.7 average from around 7 thousand ratings. Those figures suggest that many people have found the app worth trying, although popularity should never be treated as proof that a loan is affordable for every applicant.
How the app fits into a real borrowing decision
The first thing I would clarify to a friend is that a free download is not the same as a free loan. The app itself costs nothing to install, while in-app purchases are listed from $1.99 to $4.99 per item. Those are the only direct purchase figures I can responsibly use here; they should not be confused with the total cost of borrowing, repayment terms, or any offer that may appear during an application.
That distinction matters because a payday advance is not evaluated like a weather app or a note-taking tool. The important question is not simply whether the application opens quickly. It is whether the complete borrowing offer, including any applicable fees, repayment timing, and consequences of late payment, fits comfortably into the user’s next income cycle. I would read every final disclosure inside the application before accepting anything.
The app’s store positioning centers on instant cash advances and no credit check. In practical terms, that may appeal to someone who worries that a traditional lender will reject an application because of limited or damaged credit history. It does not mean approval is guaranteed, and it does not remove the need to review eligibility requirements or the final terms shown to the applicant.
I also would not treat the “instant” emphasis as a promise that money will always arrive immediately. Application review, identity checks, banking arrangements, and other processing steps can affect timing. Anyone facing a bill due within hours should have a backup plan instead of assuming that a mobile application can solve the deadline automatically.
What I would check before submitting an application
My first step would be to identify the exact amount needed, rather than applying for the largest amount that appears available. Borrowing only the shortfall makes it easier to compare the repayment against the next paycheck. I would then write down the due date for the bill, the date income is expected, and the amount that must remain available for essentials such as food, transport, utilities, and housing.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Next, I would inspect the final offer carefully. I would look for the total amount to repay, the scheduled repayment date, any fees, whether repayment is automatic, and what happens if the payment fails. A short-term advance can look manageable when viewed as a deposit today, yet become difficult when the full repayment is removed from the next pay cycle.
I would also make sure that the phone number, bank details, and identity information entered into the application are accurate. A typo in financial information can create delays or send funds to the wrong destination. Before confirming, I would save or record the offer details for my own records, including the amount received and the amount expected back.
One useful habit is to compare the app’s offer with at least one ordinary alternative before accepting it. That could mean asking an employer about an earned-wage option, contacting a utility provider about a payment arrangement, checking a credit union, or speaking directly with the bill issuer. The best alternative is not always another loan; sometimes moving the due date is cheaper than borrowing.
A realistic everyday situation
Imagine that a user’s car needs an urgent repair two days before payday. The person has enough income arriving soon but not enough cash today, and a missed repair could prevent them from getting to work. In that situation, the app’s mobile format and no-credit-check positioning may make it feel more approachable than a conventional bank application.
I would still treat it as a last-resort bridge. Before applying, I would ask the repair shop whether a partial payment is possible, whether the work can be delayed safely, or whether a less expensive repair option exists. If those routes fail, I would use the app only after confirming that the repayment will leave enough money for ordinary expenses after payday.
The same reasoning applies to rent, medical costs, groceries, or a utility bill, but the risk is different in each case. A loan that solves a small one-time timing problem may be manageable for some people. A loan used repeatedly for recurring bills points to a larger budget gap and can turn short-term borrowing into a cycle.
Where the free app provides value
The strongest value here is convenience. A dedicated mobile application can reduce the friction of starting an inquiry compared with visiting a branch or filling out a long paper form. For someone who needs to understand whether a short-term advance is even an option, having a focused place to begin may be useful.
The app also speaks to a particular audience: people who may not want a traditional credit-based application to be the first filter. The no-credit-check message can make the service feel more accessible to users who have little credit history or who have previously struggled with conventional lenders. That accessibility is valuable only when paired with clear terms and a repayment plan.
Because the download is free, a user can evaluate the application without paying an upfront app price. That is a meaningful difference from a product that charges simply to access its interface. At the same time, the presence of in-app purchases means I would not assume every part of the experience is costless. I would pay attention to any purchase prompt and make sure I understand what it buys before confirming it.
The app’s public reception is another reason it may deserve consideration. A 4.7 average across around 7 thousand ratings is a strong signal that many users have responded positively to their experience. There are also nearly 200 written reviews, which can be more useful than a star score alone because detailed comments may reveal recurring friction around applications, timing, communication, or repayment.
Still, ratings are not a substitute for reading the offer. A person may rate an app highly because it was easy to use, while the financial product itself may not be the cheapest choice for another borrower. I would use the ratings to judge general usability, not to decide whether a particular advance is affordable.
Trade-offs that are easy to overlook
The biggest trade-off is speed versus cost control. A fast application can be helpful during an emergency, but urgency makes people more likely to accept the first available option without comparing it. I would slow down at the exact moment the app encourages speed: the final review before accepting an offer.
The second trade-off is access versus repayment pressure. A no-credit-check approach may open a door that a bank closes, but the absence of a traditional credit check does not make repayment easier. The borrower still has to return the money, and the timing can matter more than the original amount.
A third practical issue is the difference between an application journey and a guaranteed result. The app can provide a route to request an advance, but users should not plan an essential payment around money that has not actually arrived. I would wait for confirmation that funds are available before committing to a purchase or promising a payment date.
Another point is repeat use. The app may seem convenient enough to keep on a phone for future emergencies, yet repeated advances can hide the fact that income is not covering regular expenses. I would use a simple rule: if repayment of one advance requires another advance, stop using the app and look for debt advice, a revised payment arrangement, or a longer-term budget solution.
Privacy and security also deserve attention in any finance application. I would install it only from the official Android store, keep the phone’s operating system protected, avoid using public Wi-Fi for sensitive submissions, and never share login or banking information with someone contacting me outside the normal application process. These precautions do not change the loan terms, but they reduce avoidable risk around financial information.
How it compares with common alternatives
Compared with a traditional bank loan, this app is more directly aimed at short-term cash access and may be more appealing to someone who does not want a conventional credit-check process. A bank or credit union may be slower or less accessible, but it can be a better route when the borrower needs a larger amount, a longer repayment period, or a more structured loan.
Compared with a credit card, a cash advance app may feel simpler because it is designed around a specific borrowing request rather than an open line of credit. A credit card can offer flexibility, but it can also encourage spending beyond the original emergency. The cheaper choice depends on the actual interest, fees, repayment schedule, and the user’s ability to clear the balance.
Compared with an employer-based earned-wage service, TriceLoans may be more relevant to someone who does not have access to that workplace benefit. An employer option may be preferable when it allows access to wages already earned with lower overall cost, but availability varies by job. I would check that option before accepting a payday advance.
Compared with asking a bill provider for an extension, borrowing is often the more complicated route. A utility company, landlord, medical provider, or service business may offer a payment arrangement that avoids creating a new debt. That conversation can feel uncomfortable, but it is worth trying when the alternative is a short repayment deadline.
Who is likely to get the most value
I see the clearest use case for someone facing a genuine, one-time timing gap, with reliable income expected soon and a repayment amount that has already been included in the budget. The app is also more suitable for a person who can read financial disclosures carefully, compare alternatives, and resist borrowing more than necessary.
It may be useful for someone whose limited credit history makes traditional borrowing difficult, provided the final offer is affordable. The free download lowers the barrier to exploring the service, and the focused design may be less intimidating than a full banking application for a first-time applicant.
I would advise a different route for anyone already behind on several bills, relying on advances every pay cycle, or unsure how repayment will fit alongside essentials. The same applies to a user who needs a large loan, wants a long repayment period, or cannot tolerate an unexpected withdrawal. A credit union, nonprofit debt counselor, employer benefit, or direct payment arrangement may be more appropriate.
Parents and guardians should also remember that the app carries an Everyone age rating, but that label does not turn borrowing into an age-free financial decision. Adults should handle applications and protect personal financial details carefully. A general content rating says little about whether a loan is suitable for a person’s circumstances.
My practical verdict on cost and value
For me, the app’s value comes from access and convenience, not from the download being free alone. It gives a focused way to explore a payday cash advance, and its strong user rating suggests that the mobile experience has worked well for many people. The current version, 1.1.6, and support for Android 7.0 or later also make it accessible to a broad range of Android users.
However, I would not recommend accepting an offer simply because the application is quick or because the app has positive ratings. The meaningful price is the full cost of the advance, not the installation price or any small in-app purchase. Since the listed purchases range from $1.99 to $4.99 per item, I would inspect each prompt and avoid paying for anything that is unclear or unnecessary to the borrowing decision.
My recommendation is conditional: consider TriceLoans only for a one-time, clearly budgeted emergency, and compare the final repayment terms with cheaper alternatives first. I would skip it if the advance is intended to cover ordinary monthly expenses, if repayment depends on another loan, or if the terms are difficult to understand.
In short, this Finance app can be a convenient starting point for people who need to investigate short-term cash access and may not qualify for a traditional credit-check route. It is not a replacement for budgeting, emergency savings, employer wage access, or lower-cost lending. If I were recommending it to a friend, I would say: use the free access to review the option, slow down before accepting anything, borrow only what is essential, and make the repayment plan the deciding factor.
Pros
- Fast application process with minimal paperwork required
- Clear repayment schedule helps users plan their budget
- May assist with urgent, short-term financial needs
- Online access makes account management convenient
- Available outside regular bank branch hours
Cons
- High fees or APR can make borrowing expensive
- Late payments may lead to additional charges
- Short repayment periods can strain limited budgets
- Approval and loan terms may vary by applicant
- Availability and conditions depend on your location
FAQs for Payday Cash Advance TriceLoans
What is Payday Cash Advance TriceLoans?
Payday Cash Advance TriceLoans appears to be a financial service designed to help users request short-term cash advances through a mobile device. Before applying, review the provider’s eligibility rules, loan amount limits, repayment schedule, and total cost. Availability may depend on your location, income, banking details, credit profile, and other information requested during the application process.
Is Payday Cash Advance TriceLoans available to everyone?
No, approval is not guaranteed for every applicant. Eligibility can depend on factors such as age, residency, employment or regular income, an active bank account, and the lender’s underwriting requirements. Some services may also be unavailable in certain states or countries. Carefully check the official terms inside the app and confirm that the service operates legally where you live before submitting personal information.
How much does a TriceLoans cash advance cost?
The cost can include interest, origination charges, service fees, late-payment fees, or other expenses, depending on the offer and applicable local regulations. Do not judge the loan only by the amount deposited into your account. Read the annual percentage rate, finance charge, repayment total, and due date carefully. If the cost is unclear, avoid accepting the offer until you receive complete written details.
How quickly can I receive money through Payday Cash Advance TriceLoans?
The application process may be completed quickly, but the time required to receive funds is not necessarily immediate. Approval, identity verification, bank processing, weekends, holidays, and the participating lender’s procedures can all affect delivery. Even when an application is accepted, the money may arrive later than expected. Confirm the estimated funding time and any expedited-transfer fee before agreeing.
Is Payday Cash Advance TriceLoans safe to use?
Use caution and verify the service before providing sensitive information such as your Social Security number, bank credentials, or income details. Download the app only from an official store or verified source, inspect its privacy policy, and check which company actually provides the loan. Never pay an upfront fee to unlock a promised loan, and remember that short-term borrowing can become expensive if repayment is missed.

Payday Cash Advance TriceLoans
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via igor.noskov.work@gmail.com, visit https://triceloans.com/, or review their https://triceloans.com/privacy-rules.php.










